

November 12, 2026 • Team Valentin, TCS Group | Keller Williams Empower
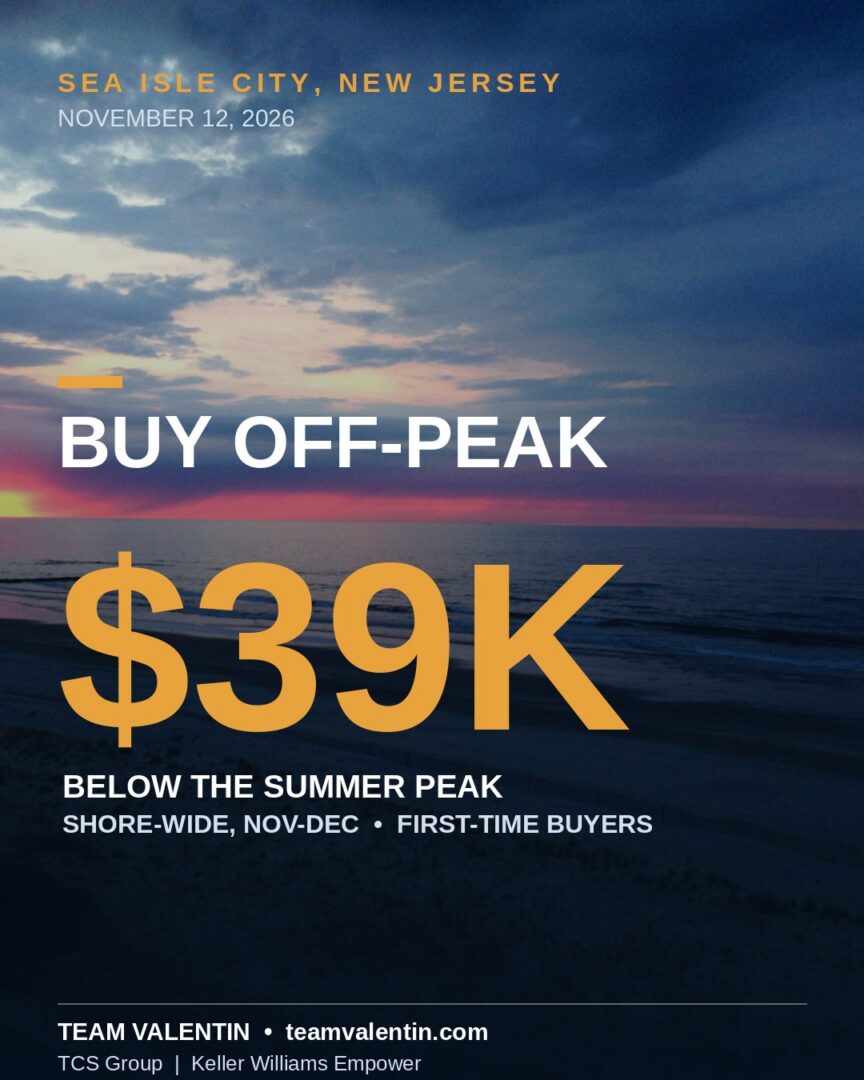
Sea Isle City in November looks nothing like Sea Isle City in July. The beach chairs are stacked, the crowds are gone, and the town belongs to the people who live there. For a first-time buyer, that quiet is the opportunity. Everyone shops the shore in summer. The buyers who get the deal shop it off-peak.
The numbers
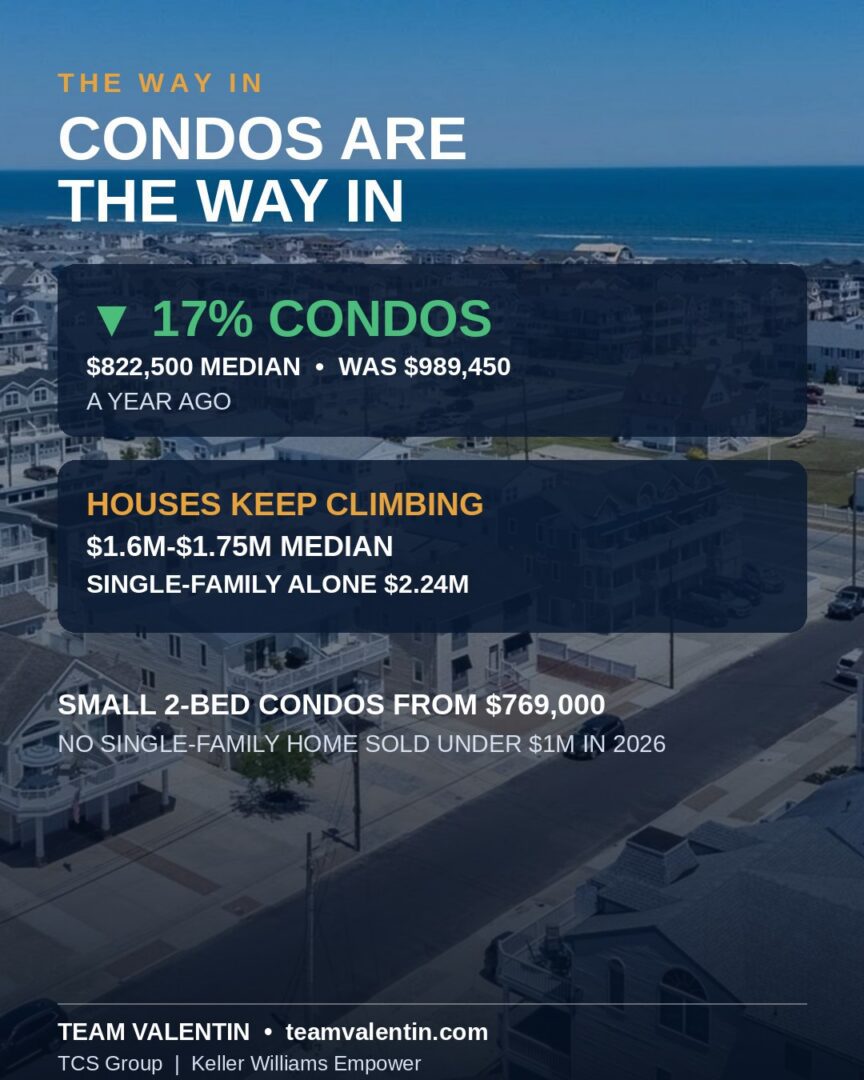
$1.6M-$1.75M — median sale price range in Sea Isle City (sources disagree; single-family homes alone median $2,235,000)
▼ 17% — condo median sale, down year over year ($989,450 to $822,500)
≈ $39,000 — shore-wide, how much lower Nov-Dec prices run vs the summer peak
43% — of fall closings land under the original asking price, vs about 1 in 3 in summer
The way in: condos, not houses
Let’s be straight about Sea Isle City prices. The overall median sits around $1.6 million to $1.75 million depending on the source, and single-family homes alone median $2,235,000. No single-family home has sold under $1 million in Sea Isle City in 2026. A first-time buyer is not starting there.
Condos are the way in. The condo median sale is down about 17% year over year, from $989,450 to $822,500, while houses kept climbing. Small older two-bedroom condos start around $769,000 to $850,000. Three that were on the market as of November 12, 2026:
- 135 65th St, Unit 7: $769,000, 2 bed / 1 bath, 832 sq ft, furnished, after a $19,000 price drop.
- 225 87th St: $773,200, 2 bed / 1 bath, 500 sq ft.
- 3700 Boardwalk, Unit 706S (The Spinnaker): $775,000, 2 bed / 2 bath oceanfront, 1,053 sq ft.
Listings move fast at the shore, so treat these as a snapshot of what the entry level looks like right now, not a guarantee any one unit is still there.
The math on a $775,000 condo
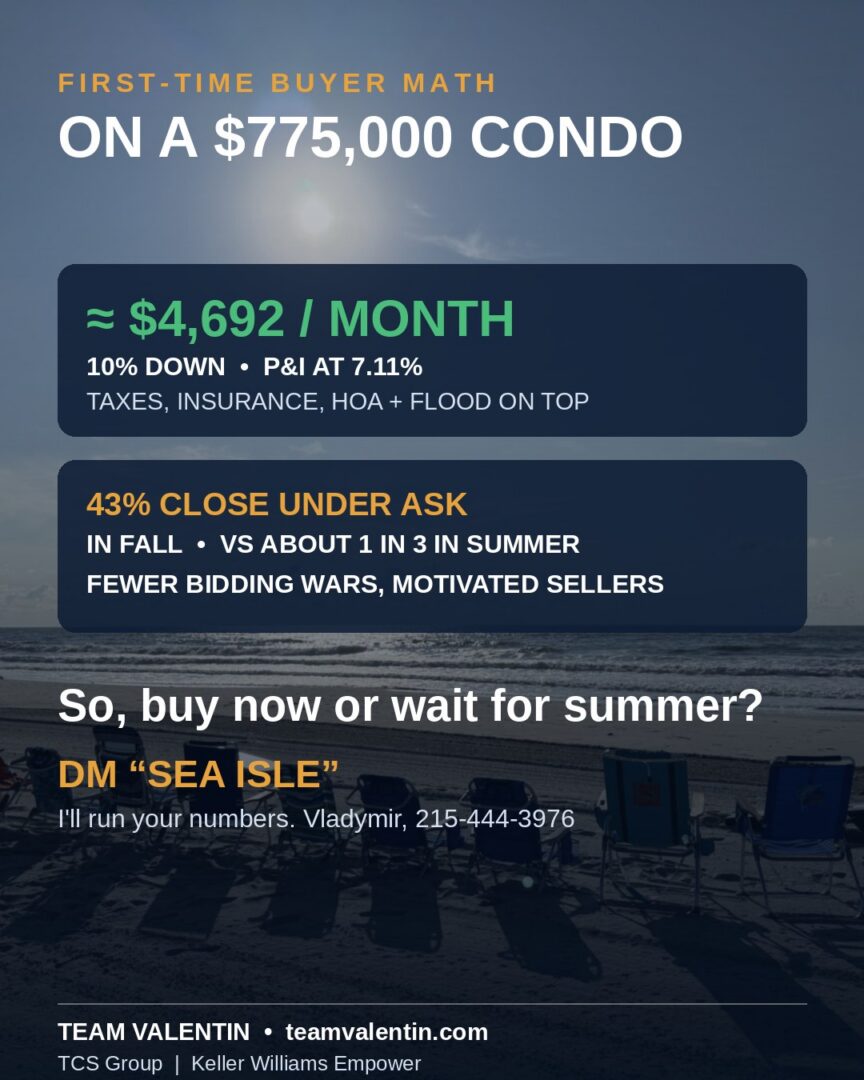
Take the $775,000 oceanfront condo above. With 10% down ($77,500), the loan is $697,500. At today’s 7.11% 30-year fixed rate, principal and interest runs about:
$4,692/mo — principal and interest only, 10% down, 7.11% 30-year fixed
That is principal and interest only. Taxes, insurance, HOA dues, flood insurance and PMI sit on top of it, so the real monthly number is higher. Two lower down-payment routes change the picture:
$5,031/mo — with FHA 3.5% down (loan $747,875), principal and interest only
$5,213/mo — with VA 0% down (loan $775,000), principal and interest only
Less cash up front means a bigger loan and a bigger monthly payment. That is the trade, and it is worth running both ways before you decide.
Why off-peak works
Off-peak does not mean sellers are desperate. It means fewer bidding wars and motivated sellers. Shore-wide, prices in November and December run about $39,000 below the summer peak, and 43% of fall closings land under the original asking price, versus about one in three in summer. You get room to negotiate, time to think, and a seller who would rather close before winter than wait for July.
Here is the twist: December is paradoxically the fastest-selling month for well-priced homes, at 30 days median days on market. The off-peak edge is negotiating room, not endless time. A good home, priced right, still moves fast.
Help that exists, and its limits
New Jersey’s down payment assistance program (NJHMFA) offers $10,000 in Cape May County. It helps, but watch the cap: the purchase-price limit is $764,069, just below today’s cheapest Sea Isle City listings at $769,000 and up. It is real help that exists, and it may not stretch to a Sea Isle City condo at today’s prices. Check the current cap before counting on it.
Flood insurance is mandatory in Sea Isle City, and it is a real line item in the budget. One thing working in your favor: the town holds a FEMA Community Rating System Class 3 rating, which carries a 35% discount on flood insurance premiums.
The rental offset, honestly
A Sea Isle City condo can gross $50,000 to $80,000 a summer in rentals. That is real money, and it can help carry the mortgage. It does not make the purchase cash-flow positive on its own, and it should not be the reason you buy. Buy the home because the payment works and you want to be there. Treat the rental income as help, not the plan.
The honest trade-offs
Waiting is a legitimate choice, and I will tell you that straight:
- If the payment at 7.11% does not fit your budget, do not stretch. A shore home you cannot comfortably afford is not a good deal at any rate.
- If you need time to save, or your job or life is in flux, waiting is smart. I work with renters too, and plenty of my clients rent right now.
- And the shore is seasonal. Winter at the beach is quiet, and some buyers love that while others miss the summer energy. Visit in November before you commit to it.
So, buy now or wait for summer?
Here is the question I ask my clients: which one fits your next three years? If you want a first home at the shore and the payment works today, buying off-peak means you negotiate while the crowds are gone, and you can refinance if rates fall. If the payment is tight or life might change, waiting is the disciplined move. What matters is the strategy, not the season.
Want to know which one fits you? DM me “SEA ISLE” on Instagram, or call or text Vladymir Valentin at 215-444-3976, and I will run the numbers on your budget, what the payment looks like today, and what buying off-peak would actually save you. Start with a strategy, end with results.
Sources: Freddie Mac Primary Mortgage Market Survey, week ending November 12, 2026 (30-year fixed 7.11%); Redfin, Zillow and Homes.com Sea Isle City listings, November 12, 2026; NJHMFA down payment assistance program; FEMA Community Rating System. Rates shown are national averages. Your rate depends on credit, down payment and loan type. Payment examples are principal and interest only, before taxes, insurance, HOA dues, flood insurance and PMI. Listing prices and availability change quickly; verify before acting.
