

November 12, 2026 • Team Valentin, TCS Group | Keller Williams Empower
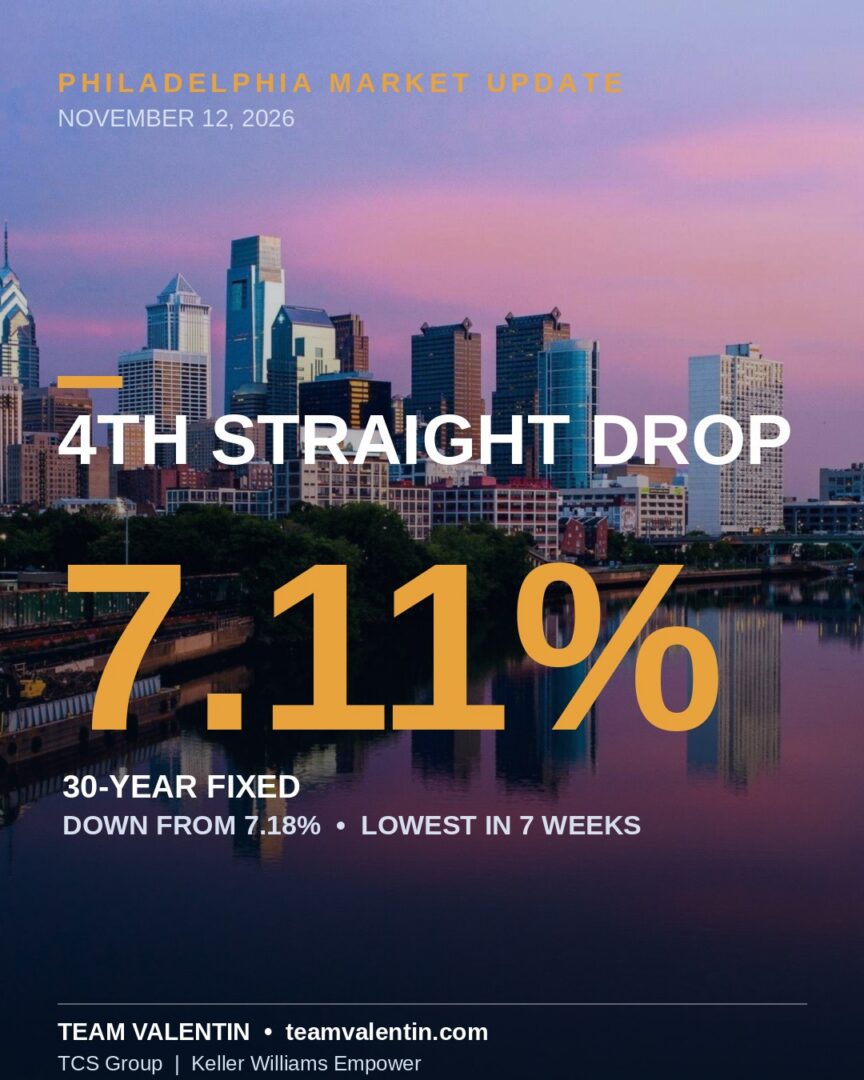
Mortgage rates fell for the fourth week in a row. The average 30-year, fixed-rate loan came in at 7.11% in the week ending Thursday, November 12 — down from 7.18% the week before, and the lowest in seven weeks. So now the question every buyer is asking: do I buy now, or wait for rates to fall further? Let’s run the real numbers, because the answer is not the same for everyone.
The numbers
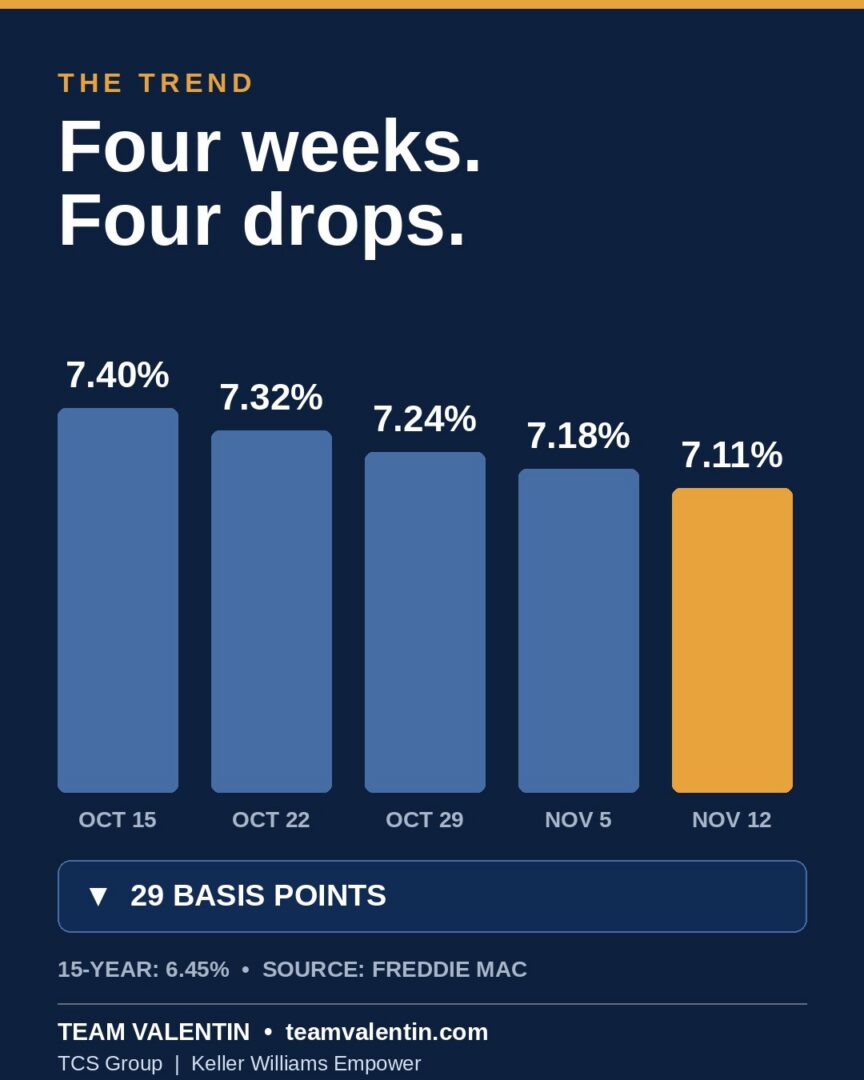
- 7.11% — 30-year fixed — down from 7.18% last week
- 6.45% — 15-year fixed — down from 6.57% last week
- 29 basis points down in four weeks (7.40% on Oct 15 to 7.11% on Nov 12)
- 6.24% — where the 30-year stood a year ago — we’re still above that
What waiting could save — on paper
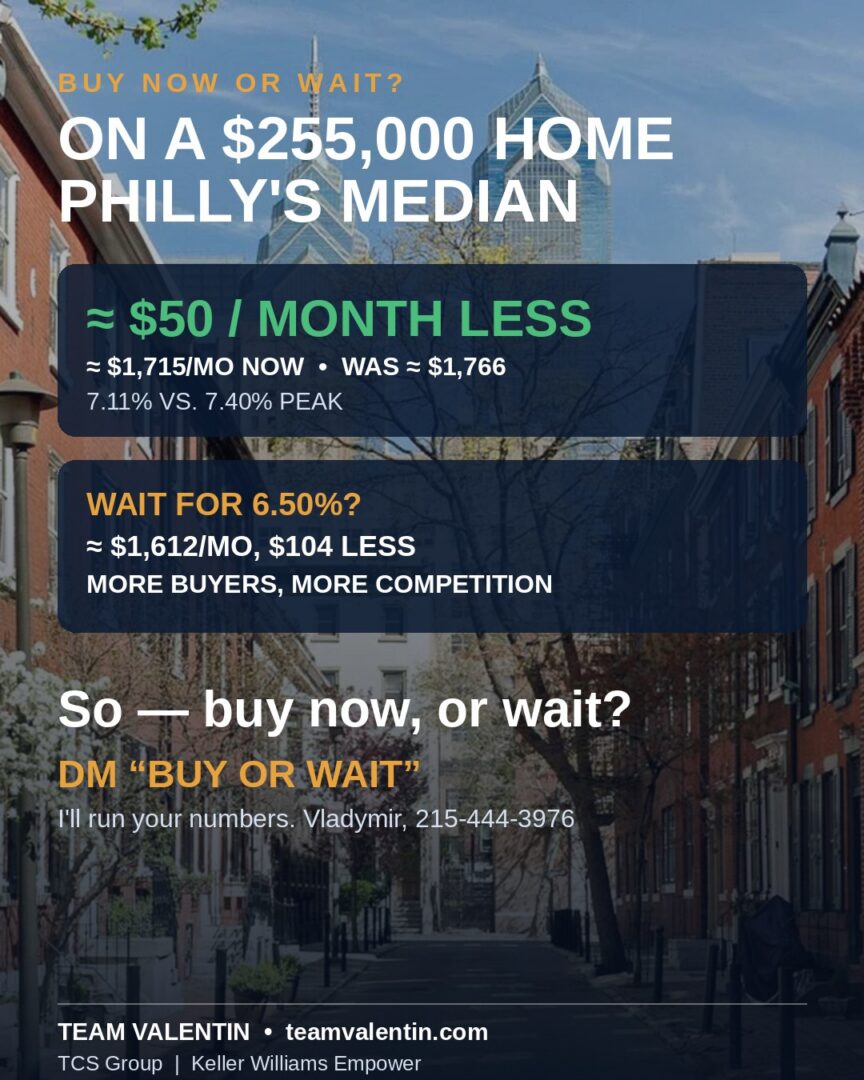
Philadelphia’s median home price is around $255,000. On a $255,000 loan, principal and interest looks like this:
- $1,766/mo — at October’s 7.40% peak
- $1,727/mo — at last week’s 7.18%
- $1,715/mo — at today’s 7.11% — about $50 a month less than the peak
- $1,612/mo — if rates fell to 6.50% — about $104 a month less than today
That last line is the one that makes people wait. And it is real money — about $1,244 a year. But it comes with two big ifs: if rates actually get to 6.50%, and if the home you want is still there, at the same price, when they do.
The case for buying now
Three things are true right now that may not be true later:
- Less competition. October existing-home sales fell to a 16-year low, and plenty of buyers are still sitting on the sidelines waiting. In Philly, that has meant buyer’s-market conditions — more room to negotiate, fewer bidding wars.
- You can refinance later. Buy the home at 7.11%, and if rates fall to 6.50% next year, you refinance into the lower rate. You keep the home and the price you negotiated. Waiting does not lock in anything.
- A lower rate does not guarantee a lower price. When rates drop, buyers flood back in — and the bidding wars come back with them. The home that costs $255,000 in a quiet market can cost more in a crowded one.
The case for waiting — honestly
Waiting is the right call for some buyers, and I will tell you that straight:
- If the payment at 7.11% does not fit your budget, do not stretch. A home you cannot comfortably afford is not a good deal at any rate.
- If you need time to save for a down payment, or your job or life is in flux, waiting is smart. The right home at the wrong time is still the wrong move.
- And nobody can promise rates keep falling. This week’s hotter-than-expected inflation report has analysts warning the relief could reverse as soon as next week, and a Fed governor floated a possible December hike. Waiting for a lower rate is a bet, not a guarantee.
So — buy now, or wait?
Here is the question I ask my clients: which one fits your next three years? If you are staying put and the payment works today, buying now means you stop paying someone else’s mortgage, and you can refinance if rates fall. If life might change, or the payment is tight, waiting is the disciplined move — and I work with renters too, so there is no wrong answer here. What matters is the strategy, not the headline rate.
Want to know which one fits you? DM me “BUY OR WAIT” on Instagram, or call or text Vladymir Valentin at 215-444-3976, and I will run the numbers on your price range — what the payment looks like today, and what waiting would actually save you. Start with a strategy, end with results.
Sources: Freddie Mac Primary Mortgage Market Survey, week ending November 12, 2026; Realtor.com, November 12, 2026; National Association of Realtors, October 2026 existing-home sales. Rates shown are national averages. Your rate depends on credit, down payment and loan type. Payment examples are principal and interest only on a $255,000 loan, before taxes, insurance and PMI.
